A Practical Guide to Smarter Coverage Choices and Lower Premiums
Auto insurance is a necessary expense for most drivers, but paying more than you need to is not. With dozens of providers, coverage types, and pricing models, comparing auto insurance options can feel confusing. The good news is that a structured approach can reveal meaningful savings without sacrificing protection.
This guide explains how to compare auto insurance options and save money, covering coverage basics, pricing factors, comparison strategies, and practical tips to reduce premiums.
Why Comparing Auto Insurance Matters
Insurance prices vary widely for the same driver and vehicle. Two companies can quote dramatically different premiums for identical coverage. Regular comparison helps you:
- Identify overpricing
- Match coverage to actual needs
- Capture new discounts
- Adjust to life changes
Comparing policies periodically is one of the most reliable ways to lower costs.
Understand the Core Types of Auto Insurance Coverage
Before comparing quotes, understand what you’re buying. The most common coverage types include:
Liability Coverage
Covers injuries and property damage you cause to others. Required in most regions.
Collision Coverage
Pays for damage to your vehicle after a collision, regardless of fault.
Comprehensive Coverage
Covers non-collision events such as theft, vandalism, fire, or weather damage.
Personal Injury Protection or Medical Payments
Covers medical expenses for you and passengers.
Uninsured or Underinsured Motorist Coverage
Protects you if you’re hit by a driver without adequate insurance.
Comparisons are only meaningful when coverage levels match.
Determine Your Coverage Needs First
Not every driver needs the same coverage. Consider:
- Vehicle value and age
- Loan or lease requirements
- Driving habits and mileage
- Local traffic and accident rates
- Personal risk tolerance
For example, older vehicles may not require collision or comprehensive coverage, which can significantly reduce premiums.
Use the Same Coverage Limits When Comparing Quotes
Always compare quotes with identical:
- Liability limits
- Deductibles
- Optional coverages
Different limits can make one policy appear cheaper when it actually provides less protection.
Compare Deductible Options Strategically
Your deductible is the amount you pay out of pocket before insurance kicks in. Higher deductibles generally lower premiums.
Ask yourself:
- Can I comfortably afford the deductible if needed?
- How often do I file claims?
Raising deductibles can produce immediate savings for low-claim drivers.
Evaluate Insurance Providers Beyond Price
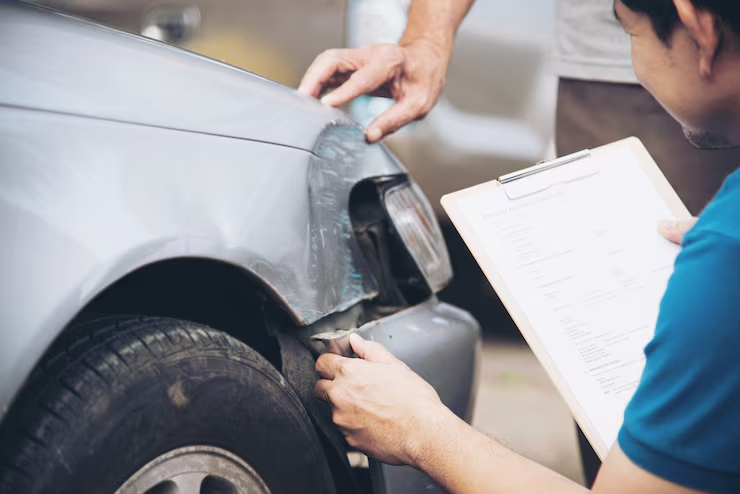
The cheapest policy isn’t always the best. Consider:
- Financial strength ratings
- Claims satisfaction scores
- Customer service reputation
- Ease of claims filing
Reliable service matters most when you need to file a claim.
Use Multiple Comparison Tools
Use a mix of:
- Online comparison platforms
- Direct insurer websites
- Independent insurance agents
Some insurers don’t appear on comparison sites, so checking directly can uncover additional savings.
Look for Discounts You May Qualify For
Discounts are a major driver of savings. Common discounts include:
- Safe driver or accident-free discounts
- Multi-policy (bundling home and auto)
- Good student discounts
- Low-mileage discounts
- Vehicle safety features
- Defensive driving courses
Ask each insurer to list all available discounts.
Bundle Policies to Lower Costs
Bundling auto insurance with homeowners, renters, or life insurance can reduce premiums significantly. Many insurers offer meaningful discounts for multi-policy customers.
Always compare bundled pricing to standalone policies to confirm actual savings.
Review Your Driving Profile Carefully
Insurance rates are based on data accuracy. Ensure your quote reflects:
- Correct annual mileage
- Accurate vehicle use (personal vs commute)
- Correct garaging location
- Up-to-date driving record
Small errors can lead to higher premiums.
Consider Usage-Based or Telematics Programs
Some insurers offer programs that track driving habits through apps or devices. Safe driving behaviors can lead to lower rates.
These programs may benefit drivers who:
- Drive infrequently
- Avoid aggressive driving
- Maintain consistent speeds
Review privacy terms before enrolling.
Don’t Automatically Renew Without Reviewing
Many drivers overpay by automatically renewing policies. Rates can increase due to:
- Market adjustments
- Claims history changes
- Risk model updates
Reviewing alternatives before renewal often reveals lower-cost options.
Adjust Coverage After Life Changes
Life events can affect insurance needs and pricing, including:
- Moving
- Marriage or divorce
- New vehicle purchase
- Retirement or reduced driving
Updating your policy after changes can unlock savings.
Pay Attention to Payment Options
How you pay can affect total cost. Some insurers offer discounts for:
- Paying annually instead of monthly
- Automatic payments
- Paperless billing
Avoid installment fees when possible.
Review Claims History Impact
Claims, even small ones, can raise premiums. When possible, consider:
- Paying minor repairs out of pocket
- Avoiding unnecessary claims
Maintaining a clean claims history supports lower long-term rates.
Compare Regional and Local Insurers
Smaller regional insurers sometimes offer competitive pricing and strong service. Don’t limit comparisons to national brands alone.
Local insurers may better understand regional risks and pricing models.
Understand How Credit Impacts Rates
In many areas, insurers use credit-based insurance scores. Improving credit health can:
- Reduce premiums
- Increase insurer options
Paying bills on time and reducing debt can lead to insurance savings over time.
Watch for Policy Add-Ons You Don’t Need
Optional add-ons can quietly increase costs. Review items such as:
- Roadside assistance
- Rental reimbursement
- Glass coverage
Some services may be cheaper through third-party providers.
Ask About Loyalty vs New Customer Pricing
Long-term loyalty doesn’t always guarantee the lowest rate. New customers may receive promotional pricing that existing customers don’t.
Asking for re-quotes or shopping competitors keeps pricing competitive.
Keep Documentation Organized
Maintain records of:
- Current policy details
- Coverage limits
- Renewal dates
Being organized simplifies comparisons and reduces errors.
When Cheaper Isn’t Better
Extremely low prices may come with:
- Poor claims handling
- Limited coverage
- Financially unstable providers
Balance savings with reliability.
How Often You Should Compare Auto Insurance
A good rule of thumb is to compare:
- Every 12 months
- Before policy renewal
- After major life changes
Regular reviews ensure continued savings.
Common Mistakes to Avoid
Avoid these pitfalls:
- Comparing mismatched coverage
- Ignoring deductibles
- Overlooking exclusions
- Assuming loyalty equals savings
Awareness prevents costly errors.
Long-Term Strategies to Lower Auto Insurance Costs
Over time, you can reduce rates by:
- Maintaining a clean driving record
- Improving credit
- Choosing vehicles with lower insurance costs
- Reducing annual mileage
Smart habits compound savings.
Final Thoughts
Comparing auto insurance options doesn’t require expert knowledge — just structure, consistency, and attention to detail. By understanding coverage, shopping strategically, and reviewing policies regularly, drivers can secure meaningful savings without compromising protection.
Auto insurance should protect your financial future, not strain it. With the right approach, comparing options becomes a powerful tool to lower costs and drive with confidence.