Financial Security, Stability, and Peace of Mind for the People You Love
Life insurance is one of the most important financial tools for protecting your family’s future. While it can be uncomfortable to think about worst-case scenarios, planning ahead ensures that your loved ones are financially supported if the unexpected happens.
This article explains how life insurance policies protect your family, what types of coverage are available, and how to choose the right policy to provide long-term security and peace of mind.
Why Life Insurance Matters for Families
Life insurance provides a financial safety net when income is suddenly lost. Without coverage, families may struggle to pay everyday expenses, manage debt, or maintain their standard of living.
Life insurance helps:
- Replace lost income
- Cover essential living costs
- Pay off debts and obligations
- Protect long-term financial goals
For many families, it is the foundation of financial protection.
What Is Life Insurance?
Life insurance is a contract between you and an insurance provider. In exchange for regular premium payments, the insurer agrees to pay a benefit to your beneficiaries if you pass away during the policy period.
This benefit can be used however your family needs it, offering flexibility and security during a difficult time.
How Life Insurance Provides Income Replacement
One of the primary roles of life insurance is income replacement. If you are a primary earner, your policy can help your family continue to pay for:
- Housing and utilities
- Food and daily expenses
- Transportation
- Childcare and education
Replacing income prevents sudden financial hardship and gives your family time to adjust.
Covering Mortgage and Housing Costs
For most families, housing is the largest expense. Life insurance proceeds can be used to:
- Pay off a mortgage
- Cover rent payments
- Handle property taxes and maintenance
This helps ensure your family can remain in their home rather than facing relocation or foreclosure.
Paying Off Outstanding Debts
Debt does not disappear after death. Life insurance can help pay:
- Credit cards
- Personal loans
- Auto loans
- Medical bills
By eliminating debt, life insurance prevents financial obligations from becoming a burden for surviving family members.
Supporting Children’s Education
Life insurance can help secure your children’s future by funding:
- School tuition
- College education
- Training programs
Education costs continue to rise, and life insurance ensures your children’s opportunities are protected even if your income is no longer available.
Providing for Daily Living Expenses
Beyond large expenses, families rely on steady income for daily life. Life insurance benefits help cover:
- Groceries
- Clothing
- Healthcare
- Transportation
This financial continuity allows families to maintain stability during an emotionally challenging period.
Types of Life Insurance Policies
Understanding policy types helps you choose the right protection for your family.
Term Life Insurance
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. It is often:
- More affordable
- Simple and straightforward
- Ideal for income replacement during working years
If the policyholder passes away during the term, beneficiaries receive the payout.
Whole Life Insurance
Whole life insurance provides lifelong coverage and includes a savings component. Features include:
- Guaranteed death benefit
- Cash value accumulation
- Stable premiums
This option offers both protection and long-term financial planning benefits.
Universal Life Insurance
Universal life insurance offers flexible premiums and adjustable coverage. It allows:
- Changes to coverage amounts
- Potential cash value growth
- Long-term family protection
This flexibility suits families with evolving financial needs.
Choosing Beneficiaries Wisely
Naming beneficiaries ensures life insurance benefits go directly to intended recipients. This helps:
- Avoid probate delays
- Provide immediate financial support
- Ensure clarity and control
Beneficiaries can include spouses, children, trusts, or other dependents.
Protecting Stay-at-Home Parents
Even if one parent does not earn income, their contribution has significant financial value. Life insurance can help cover:
- Childcare costs
- Household services
- Transportation needs
Coverage ensures the family can replace essential services if needed.
Supporting Single-Parent Households
For single parents, life insurance is especially critical. It helps:
- Secure children’s financial future
- Cover guardianship-related expenses
- Provide stability in the absence of income
This protection is often a top priority for single-parent families.
Helping With Final Expenses
Life insurance can also cover final expenses such as:
- Funeral and burial costs
- Memorial services
- Legal and administrative fees
This prevents families from facing sudden financial strain during a difficult time.
Tax Advantages of Life Insurance
Life insurance benefits are generally paid tax-free to beneficiaries. This means:
- The full benefit amount is available
- No income tax burden for recipients
Tax efficiency makes life insurance a powerful planning tool.
Life Insurance and Long-Term Financial Planning
Life insurance fits into broader financial planning by:
- Supporting estate planning
- Providing liquidity
- Protecting wealth for future generations
It complements savings, investments, and retirement planning.
How Much Life Insurance Coverage Is Enough?
Coverage needs vary based on:
- Income level
- Family size
- Debt obligations
- Long-term goals
A common approach is to consider coverage that replaces several years of income while covering major expenses.
Life Insurance at Different Life Stages
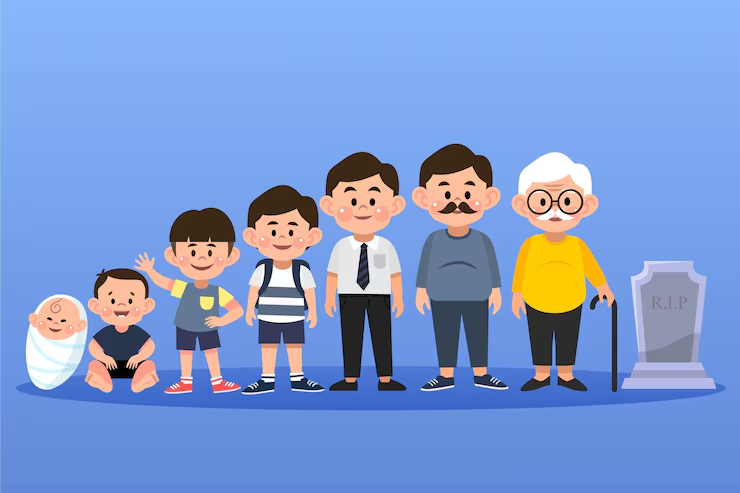
Life insurance needs evolve over time.
Young Families
Coverage helps protect growing households and rising expenses.
Established Families
Higher coverage supports mortgages, education, and lifestyle costs.
Empty Nesters
Policies may shift toward estate planning and legacy goals.
Regular reviews ensure coverage stays aligned with family needs.
Common Misconceptions About Life Insurance
Misconceptions include:
- Life insurance is only for older individuals
- Coverage is too expensive
- Only the main earner needs insurance
In reality, policies are often affordable and valuable at many life stages.
How Life Insurance Reduces Emotional Stress
Beyond financial benefits, life insurance provides peace of mind. Knowing your family is protected allows you to:
- Focus on living fully
- Reduce anxiety about the future
- Make confident financial decisions
This emotional security is a powerful benefit.
Reviewing and Updating Your Policy
Life changes such as marriage, children, or career growth should prompt a policy review. Updates ensure:
- Coverage remains adequate
- Beneficiaries are current
- Premiums align with needs
Regular reviews keep protection relevant.
When Life Insurance May Not Be Necessary
Life insurance may be less critical if:
- No financial dependents exist
- Substantial assets already cover needs
However, many individuals still choose coverage for final expenses or legacy planning.
How to Get Started With Life Insurance
Getting started involves:
- Assessing family needs
- Comparing policy options
- Choosing appropriate coverage
- Naming beneficiaries
Professional guidance can simplify the process.
Final Thoughts
Life insurance is a powerful way to protect your family’s financial future. By replacing income, covering major expenses, eliminating debt, and supporting long-term goals, it provides stability during life’s most uncertain moments.
Choosing the right life insurance policy ensures your loved ones are cared for, your plans remain intact, and your family has the resources they need to move forward with confidence. Thoughtful preparation today creates security and peace of mind for tomorrow.