Cutting Through the Confusion to Get the Right Protection at the Right Price
Auto insurance can feel overwhelming. With a long list of coverage options, add-ons, and legal requirements, many drivers end up either underinsured or paying for protection they don’t really need. Understanding what coverage matters—and when—helps you protect your finances without overspending.
This guide explains what auto insurance coverage you actually need, how to decide appropriate limits, and how to avoid common coverage mistakes.
Why Choosing the Right Coverage Matters
Auto insurance isn’t just a legal requirement—it’s financial protection. The right coverage:
- Shields you from costly lawsuits
- Covers medical expenses after accidents
- Protects your vehicle investment
- Prevents out-of-pocket financial shocks
The wrong coverage can leave dangerous gaps or inflate premiums unnecessarily.
The Core Coverages Every Driver Needs
Most drivers need a core set of coverages. These form the foundation of a sound auto insurance policy.
Liability Coverage
Liability coverage is required in most regions and is the most important coverage you carry. It pays for:
- Injuries you cause to others
- Damage you cause to other vehicles or property
What Limits You Actually Need
Minimum legal limits are often too low to protect your assets. Higher limits help cover:
- Medical bills
- Legal fees
- Property damage
If you have savings, property, or future income to protect, higher liability limits are essential.
Uninsured and Underinsured Motorist Coverage
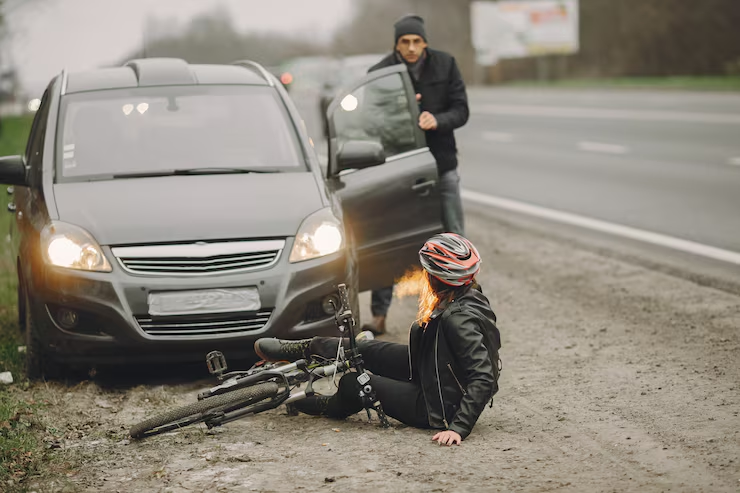
Not all drivers carry sufficient insurance. This coverage protects you if you’re hit by someone who:
- Has no insurance
- Has insurance that doesn’t cover your losses
This coverage often pays for:
- Medical expenses
- Lost wages
- Pain and suffering
In areas with high uninsured driver rates, this coverage is especially important.
Medical Payments or Personal Injury Protection
These coverages help pay medical costs after an accident, regardless of fault. They can cover:
- Hospital visits
- Doctor fees
- Rehabilitation
If you have strong health insurance, you may need lower limits—but some coverage still provides valuable flexibility.
Vehicle Protection Coverages: When You Need Them
These coverages protect your own vehicle. Whether you need them depends on your car’s value and your financial situation.
Collision Coverage
Collision coverage pays to repair or replace your vehicle after an accident—regardless of fault.
You Likely Need Collision If:
- Your car is newer or has high value
- You are financing or leasing the vehicle
- You can’t afford to replace your car out of pocket
You May Skip Collision If:
- Your vehicle has low market value
- Repair costs would exceed the car’s worth
- You have savings to replace it yourself
Comprehensive Coverage
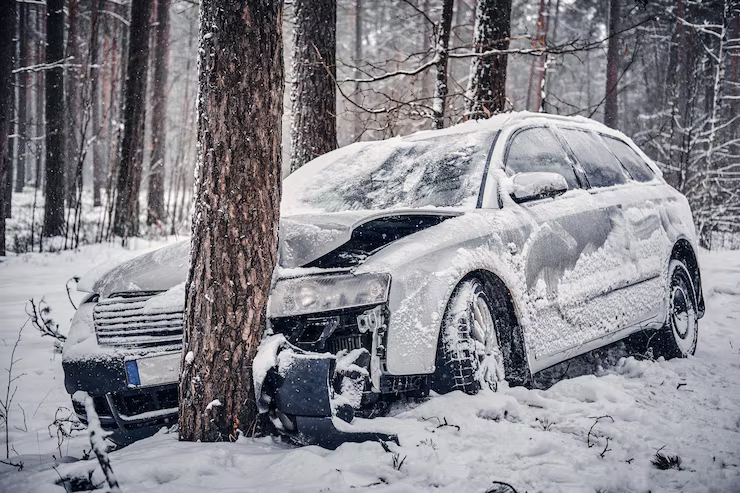
Comprehensive coverage protects against non-collision events such as:
- Theft
- Fire
- Vandalism
- Weather damage
- Animal collisions
This coverage is usually affordable and valuable for most drivers with cars worth more than a minimal amount.
Deductibles: Where You Control Cost
Your deductible is what you pay before insurance covers a claim.
Smart Deductible Strategy
- Higher deductibles lower premiums
- Choose a deductible you can comfortably afford
- Avoid ultra-low deductibles that inflate monthly costs
Balancing deductible and premium keeps coverage affordable and practical.
Optional Coverages: Useful or Unnecessary?
Some add-ons are helpful, while others may duplicate services you already have.
Roadside Assistance
Covers towing, lockouts, flat tires, and jump-starts.
Consider skipping if:
- You already have roadside coverage through an auto club, credit card, or vehicle warranty
Rental Reimbursement
Pays for a rental car while your vehicle is being repaired after a covered claim.
Worth considering if:
- You rely heavily on your vehicle
- You don’t have easy transportation alternatives
Gap Insurance
Gap coverage pays the difference between what your car is worth and what you owe on a loan.
Essential if:
- You financed with a small down payment
- Your loan balance exceeds vehicle value
Once your loan balance drops, this coverage becomes unnecessary.
Coverage Based on Life Stage and Driving Habits
Your ideal coverage changes over time.
New Drivers and Young Adults
Young drivers often benefit from:
- Higher liability limits
- Uninsured motorist protection
- Modest deductibles
Avoid over-insuring older vehicles they drive.
Families and Multi-Car Households
Families may need:
- Higher liability limits
- Rental reimbursement
- Comprehensive coverage on multiple vehicles
Bundling policies can reduce overall cost.
Seniors and Low-Mileage Drivers
Low-mileage drivers may reduce costs by:
- Lowering coverage where appropriate
- Exploring usage-based insurance programs
Coverage still matters—even for infrequent driving.
How Much Coverage Is Enough?
A practical rule:
- Carry enough liability to protect assets
- Insure your vehicle only to its real value
- Avoid paying for duplicate services
Your coverage should match risk—not fear.
Common Auto Insurance Mistakes to Avoid
Avoid these costly errors:
- Carrying only minimum liability limits
- Insuring low-value cars with full coverage
- Ignoring uninsured motorist protection
- Automatically renewing without review
Regular reviews prevent overpayment and gaps.
How Often You Should Review Coverage
Review your policy:
- Once per year
- After buying or selling a car
- After moving or changing jobs
- When finances improve
Coverage should evolve with your life.
Balancing Cost and Protection
Cheapest is not always safest. The goal is:
- Adequate protection
- Manageable premiums
- Predictable financial risk
Strategic coverage selection delivers peace of mind without waste.
When More Coverage Makes Sense
You may need higher coverage if you:
- Own a home
- Have savings or investments
- Earn a high income
Insurance protects future earnings as much as current assets.
When Less Coverage Is Reasonable
You may safely reduce coverage if:
- Your vehicle has minimal value
- You have emergency savings
- You can self-insure smaller losses
This approach can significantly lower premiums.
Understanding Policy Language Before Buying
Always confirm:
- Coverage limits
- Exclusions
- Claim requirements
Clarity prevents unpleasant surprises.
Final Thoughts
Auto insurance doesn’t need to be complicated. The coverage you actually need depends on your vehicle’s value, your financial situation, and your tolerance for risk—not on upsells or legal minimums.
By focusing on strong liability protection, appropriate vehicle coverage, and eliminating unnecessary add-ons, you can build an insurance policy that protects what matters most while keeping costs under control.
Smart coverage choices today prevent financial stress tomorrow.