Medicare plays a central role in healthcare coverage for millions of Americans, yet many people find it confusing when they first enroll. One of the biggest challenges is understanding how Medicare plans differ by coverage type. Each option serves a different purpose, offers different benefits, and comes with different costs and rules.
Choosing the right Medicare coverage often depends on healthcare needs, budget, lifestyle, and preferences for provider access. Knowing how each plan type works helps individuals avoid unexpected costs and coverage gaps.
This guide explains how Medicare plans differ by coverage type, what each option covers, and how they compare in everyday use.
Understanding The Structure Of Medicare
Medicare is divided into several parts, each covering specific healthcare services. These parts can be combined in different ways to form complete coverage.
The main coverage types include:
- Original Medicare
- Medicare Advantage plans
- Medicare supplement plans
- Prescription drug plans
Each type addresses different healthcare needs and cost considerations.
Original Medicare Coverage
Original Medicare is the foundation of the Medicare program. It is administered by the federal government and consists of two parts.
Part A Hospital Coverage
Part A helps cover inpatient hospital care and related services.
It generally includes:
- Hospital stays
- Skilled nursing facility care after hospitalization
- Hospice care
- Limited home health services
Most people do not pay a monthly premium for Part A, but deductibles and coinsurance may apply.
Part B Medical Coverage
Part B focuses on outpatient and preventive care.
It typically covers:
- Doctor visits
- Outpatient services
- Preventive screenings
- Diagnostic tests
- Durable medical equipment
Part B requires a monthly premium and includes cost sharing such as deductibles and coinsurance.
How Original Medicare Coverage Works In Practice
With Original Medicare, beneficiaries can see any provider that accepts Medicare nationwide. There are no networks and no referral requirements.
However, Original Medicare does not cover everything. Beneficiaries are responsible for:
- Deductibles
- Coinsurance
- Copayments
- Certain services not covered
This is why many people consider additional coverage options.
Medicare Supplement Coverage
Medicare supplement plans, often called Medigap plans, are designed to work alongside Original Medicare.
They help cover costs such as:
- Part A deductibles
- Part B coinsurance
- Hospital coinsurance for extended stays
- Skilled nursing facility coinsurance
These plans do not replace Medicare. Instead, they reduce out-of-pocket expenses.
How Medicare Supplements Differ From Other Plans
Medicare supplement plans are standardized, meaning coverage is the same for each plan type regardless of the insurance company.
Key characteristics include:
- Predictable costs
- Broad provider access
- No network restrictions
- Higher monthly premiums but lower out-of-pocket costs
Supplements do not include prescription drug coverage, which must be obtained separately.
Medicare Advantage Coverage
Medicare Advantage plans offer an alternative way to receive Medicare benefits. These plans are provided by private insurance companies and combine multiple types of coverage into one plan.
They typically include:
- Hospital coverage
- Medical coverage
- Often prescription drug coverage
- Additional benefits not covered by Original Medicare
Medicare Advantage plans replace Original Medicare for coverage while enrolled.
How Medicare Advantage Coverage Differs
Medicare Advantage plans operate differently from Original Medicare.
Common features include:
- Provider networks
- Copayments for services
- Annual out-of-pocket maximums
- Plan-specific rules and coverage
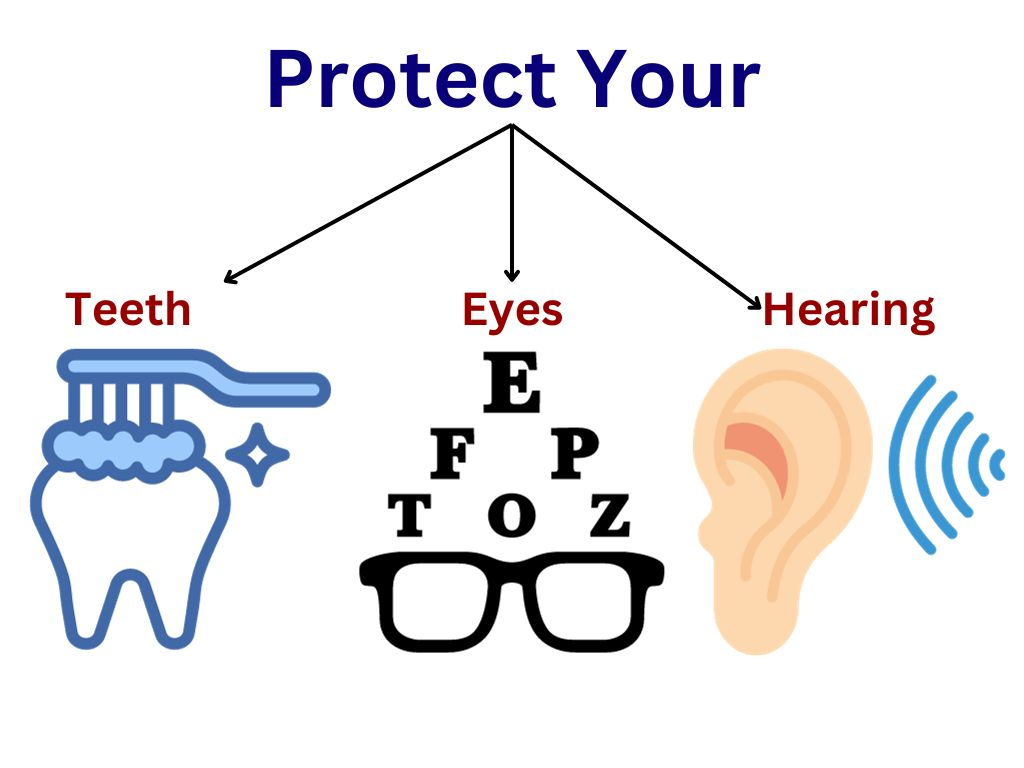
These plans may include extra benefits such as dental, vision, hearing, and wellness programs.
Prescription Drug Coverage Differences
Prescription drug coverage is handled separately under Medicare.
Standalone Drug Plans
These plans are used with Original Medicare or Medicare supplement coverage.
They help cover:
- Prescription medications
- Pharmacy costs
- Drug formularies based on plan rules
Costs vary depending on medications and pharmacy use.
Drug Coverage Within Medicare Advantage
Many Medicare Advantage plans include prescription drug coverage as part of the plan.
This bundled approach:
- Simplifies coverage management
- Combines medical and drug benefits
- Uses plan-specific formularies
Not all Advantage plans include drug coverage, so review is important.
Comparing Coverage Flexibility
One of the biggest differences between Medicare coverage types is flexibility.
Original Medicare with a supplement:
- Allows nationwide provider access
- Does not require referrals
- Offers consistent coverage
Medicare Advantage:
- Uses networks
- May require referrals
- Varies by plan and location
Choosing depends on how much flexibility a person wants.
Cost Structure Differences By Coverage Type
Each Medicare coverage type handles costs differently.
Original Medicare:
- Lower premiums for Part A
- Monthly Part B premium
- No annual out-of-pocket maximum
Medicare supplements:
- Higher monthly premiums
- Minimal out-of-pocket expenses
Medicare Advantage:
- Lower or zero premiums in some cases
- Copayments for services
- Annual out-of-pocket limits
Understanding these differences helps with budgeting.
Coverage For Preventive And Routine Care
All Medicare coverage types include preventive care, but access may differ.
Preventive services may include:
- Annual wellness visits
- Screenings
- Vaccinations
Original Medicare provides standardized preventive benefits, while Medicare Advantage plans may add extra wellness offerings.
Coverage While Traveling
Travel considerations can influence plan choice.
Original Medicare with a supplement:
- Offers nationwide coverage
- May include limited foreign emergency coverage
Medicare Advantage:
- Typically limited to service areas
- Emergency coverage still applies
- Routine care may be restricted when traveling
Frequent travelers often prioritize broader provider access.
Enrollment Rules And Timing Differences
Enrollment opportunities differ by coverage type.
Original Medicare:
- Initial enrollment when first eligible
- Special enrollment periods may apply
Medicare supplements:
- Best enrolled during initial eligibility
- Later enrollment may involve medical underwriting
Medicare Advantage:
- Annual enrollment periods
- Plan changes allowed during specific windows
Understanding timing helps avoid coverage gaps.
Choosing The Right Coverage Type
The best Medicare coverage depends on individual circumstances.
Consider factors such as:
- Health conditions
- Frequency of medical care
- Prescription needs
- Budget
- Provider preferences
- Travel habits
No single plan is best for everyone.
Common Misunderstandings About Medicare Coverage Types
Many people assume:
- All Medicare plans cover the same services
- Lower premiums always mean lower costs
- Advantage plans and supplements work the same way
In reality, coverage differences can significantly impact access and expenses.
Final Thoughts
Medicare plans differ by coverage type in how they handle costs, provider access, benefits, and flexibility. Original Medicare, Medicare supplements, Medicare Advantage plans, and prescription drug plans each serve distinct roles in the Medicare system.
Understanding how Medicare plans differ by coverage type allows individuals to make informed decisions that align with their healthcare needs and financial priorities. Taking time to compare options can help ensure stable, reliable coverage now and in the future.